Mapping Chad's banking sector: current situation and prospects
Chad's banking sector operates within a regional environment structured around two major African monetary zones: CEMAC, the Economic and Monetary Community of Central Africa, and UEMOA, the West African Economic and Monetary Union. Both use a CFA franc pegged to the euro.
Despite this monetary similarity, their banking-development paths differ significantly. This article maps Chad's banking system within its regional context, examining its strengths, weaknesses and prospects.
1. CEMAC and UEMOA: contrasting dynamics
A comparison reveals a significant gap in banking development.
Key indicators
• UEMOA has around 2.5 times as many banks as CEMAC: 136 versus 54.
• Bank accounts are approximately five times more numerous: 22.6 million versus 4.1 million.
• Banking penetration is estimated at 26% in UEMOA versus 14% in CEMAC.
These figures reflect a structural reality: UEMOA's banking ecosystem is more mature, dense and structured, while CEMAC remains an emerging market with low banking penetration.
The gap also explains West Africa's lead in digital financial services and Mobile Money's rapid rise as a complement to banks.
2. CEMAC's banking structure
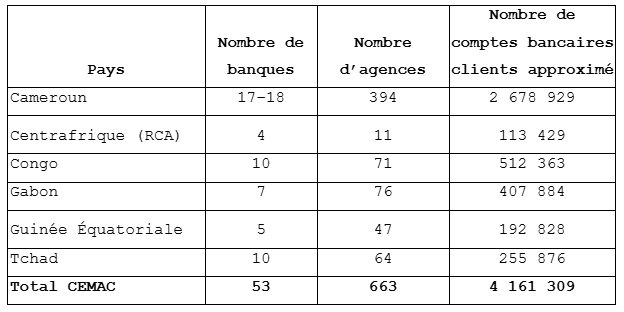
Banking activity is unevenly distributed across CEMAC.
Regional distribution
BEAC data, 2023
Analysis
Cameroon dominates the region with nearly 60% of branches and over 50% of bank accounts.
This reflects a more dynamic economy, greater relative stability and the presence of regional financial institutions.
3. Mapping Chad's banking system
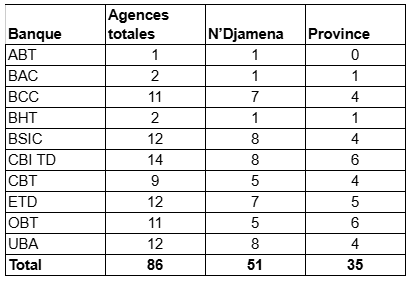
3.1 Branch-network structure
Chad's banking sector remains underdeveloped and highly concentrated:
• around ten operating banks;
• fewer than 90 branches;
• over 50% of branches in N'Djamena.
Branch distribution, 2026
These data indicate strong urban concentration, limited geographic coverage and very small networks at some banks, with only one or two branches.
For an estimated population of 20 million, this illustrates a substantial financial-inclusion gap.
3.2 Card and electronic-payment activity in Chad
Cards, ATMs, POS terminals and electronic payments remain underdeveloped:
• fewer than 200,000 active cards;
• some banks have fewer than four ATMs;
• around 50% of banks do not offer POS terminals;
• several banks have no mobile application.
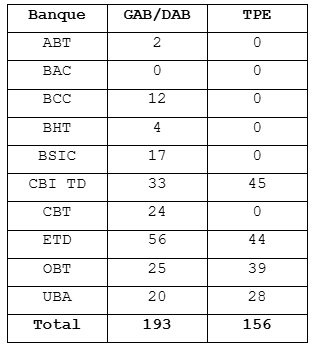
Payment infrastructure also has considerable room to develop. The following table summarises ATMs and POS terminals across Chad's banking network.
The market data reveal strong cash dependence, low electronic-payment adoption and incomplete digitalisation.
Some banks, particularly UBA, Ecobank, Coris and Orabank, stand out for their investment in card-payment infrastructure.
4. Issues and challenges
Major challenges:
• Low banking penetration.
• Geographic concentration.
• Technological delays.
• Mobile Money competition.
5. Opportunities and prospects
Despite these constraints, Chad's market has considerable potential, including digital public services.
Opportunities:
• A largely untapped market.
• Limited effective competition in some segments.
• Growing need for digital financial services.
• Gradual digitalisation of public services.
Trends to watch:
• Mobile banking development.
• Fintech expansion.
• Digital lending growth.
• Mobile Money interoperability.
A recent example
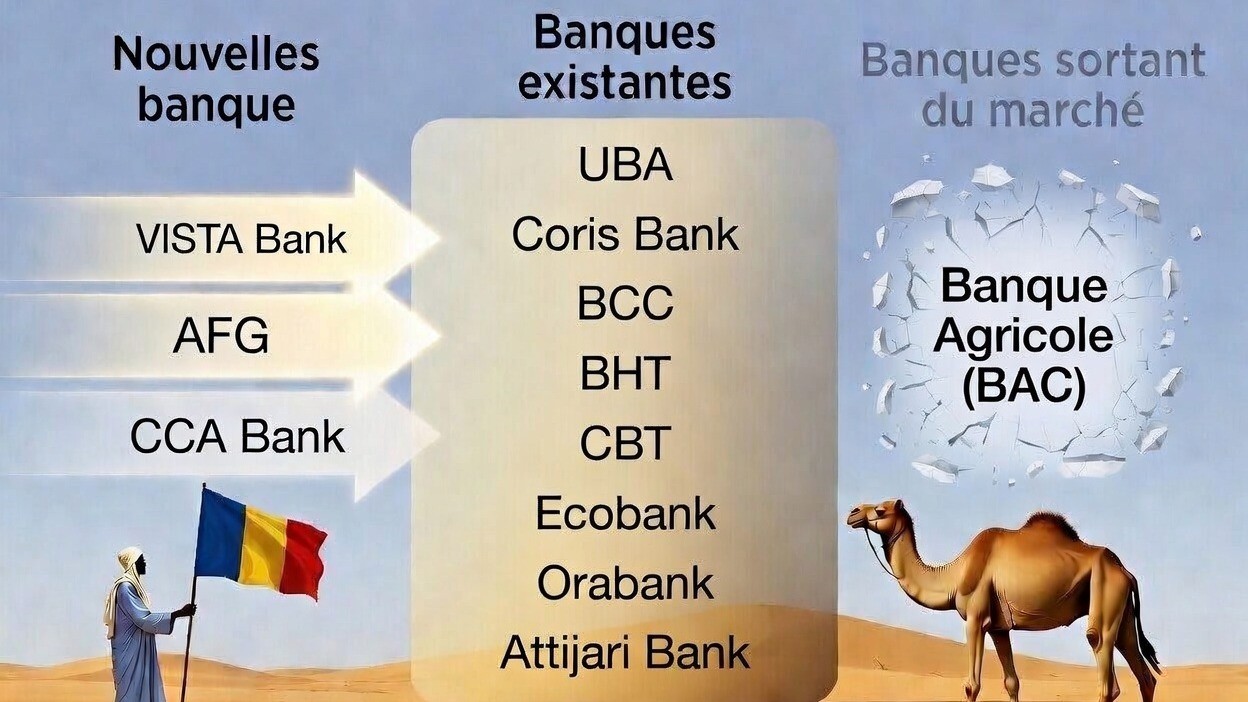
New entrants, including acquisitions such as VISTA's purchase of Banque Agricole, illustrate growing interest in the market.
Chad's banking sector is at a strategic turning point.
On one side are an underdeveloped market, low financial inclusion and limited infrastructure. On the other are substantial growth potential, opportunities for innovation and increasing demand for modern financial services.
The successful participants will be those able to offer appropriate digital solutions, expand beyond major cities and deliver a simple, accessible customer experience.
Chad is therefore a real opportunity for banks and fintechs willing to invest in an untapped but promising market.
If you enjoyed this article, please comment, share and follow this page.
Legend
ABT: Attijari Bank Tchad.
BAC: Banque Agricole et Commerciale.
BCC: Banque Commerciale du Chari.
BHT: Banque de l'Habitat du Tchad.
BSIC: Banque Sahélo Saharienne pour l'investissement et le commerce.
CBI TD: Coris Bank International Tchad.
CBT: Commercial Bank Tchad.
ETD: Ecobank.
OBT: Orabank Tchad.
UBA: United Bank for Africa.
Sources:
https://ecofinances.net/2025/05/05/zone-cemac-le-taux-de-bancarisation-atteint-14-en-2023-contre-26-pour-la-zone-uemoa/
https://cb-umoa.org/fr/paysage-des-assujetis
https://www.beac.int/wp-content/uploads/2016/10/RAPPORT-SUR-LES-SERVICES-DE-PAIEMENT-DANS-LA-CEMAC2.pdf
CEMAC banking sector
| Country | Number of banks | Branches | Customer bank accounts (approx.) |
|---|---|---|---|
| Cameroon | 17–18 | 394 | 2 678 929 |
| Central African Republic | 4 | 11 | 113 429 |
| Congo | 10 | 71 | 512 363 |
| Gabon | 7 | 76 | 407 884 |
| Equatorial Guinea | 5 | 47 | 192 828 |
| Chad | 10 | 64 | 255 876 |
| CEMAC total | 53 | 663 | 4 161 309 |
Bank branches in Chad
| Bank | Total branches | N’Djamena | Outside N’Djamena |
|---|---|---|---|
| ABT | 1 | 1 | 0 |
| BAC | 2 | 1 | 1 |
| BCC | 11 | 7 | 4 |
| BHT | 2 | 1 | 1 |
| BSIC | 12 | 8 | 4 |
| CBI TD | 14 | 8 | 6 |
| CBT | 9 | 5 | 4 |
| ETD | 12 | 7 | 5 |
| OBT | 11 | 5 | 6 |
| UBA | 12 | 8 | 4 |
| Total | 86 | 51 | 35 |
ATMs and POS terminals in Chad
| Bank | ATMs | POS terminals |
|---|---|---|
| ABT | 2 | 0 |
| BAC | 0 | 0 |
| BCC | 12 | 0 |
| BHT | 4 | 0 |
| BSIC | 17 | 0 |
| CBI TD | 33 | 45 |
| CBT | 24 | 0 |
| ETD | 56 | 44 |
| OBT | 25 | 39 |
| UBA | 20 | 28 |
| Total | 193 | 156 |